cooprueda
The lifelong savings circle, now with a guarantee fund and a path to cheap credit: people with no credit file already save in groups — Rueda simply backs it and records it.
- CLIENT
- own product — 100% Dominican cooperative
- YEAR
- 2026
- DURATION
- ongoing
- CATEGORY
- fintech / savings & credit cooperative
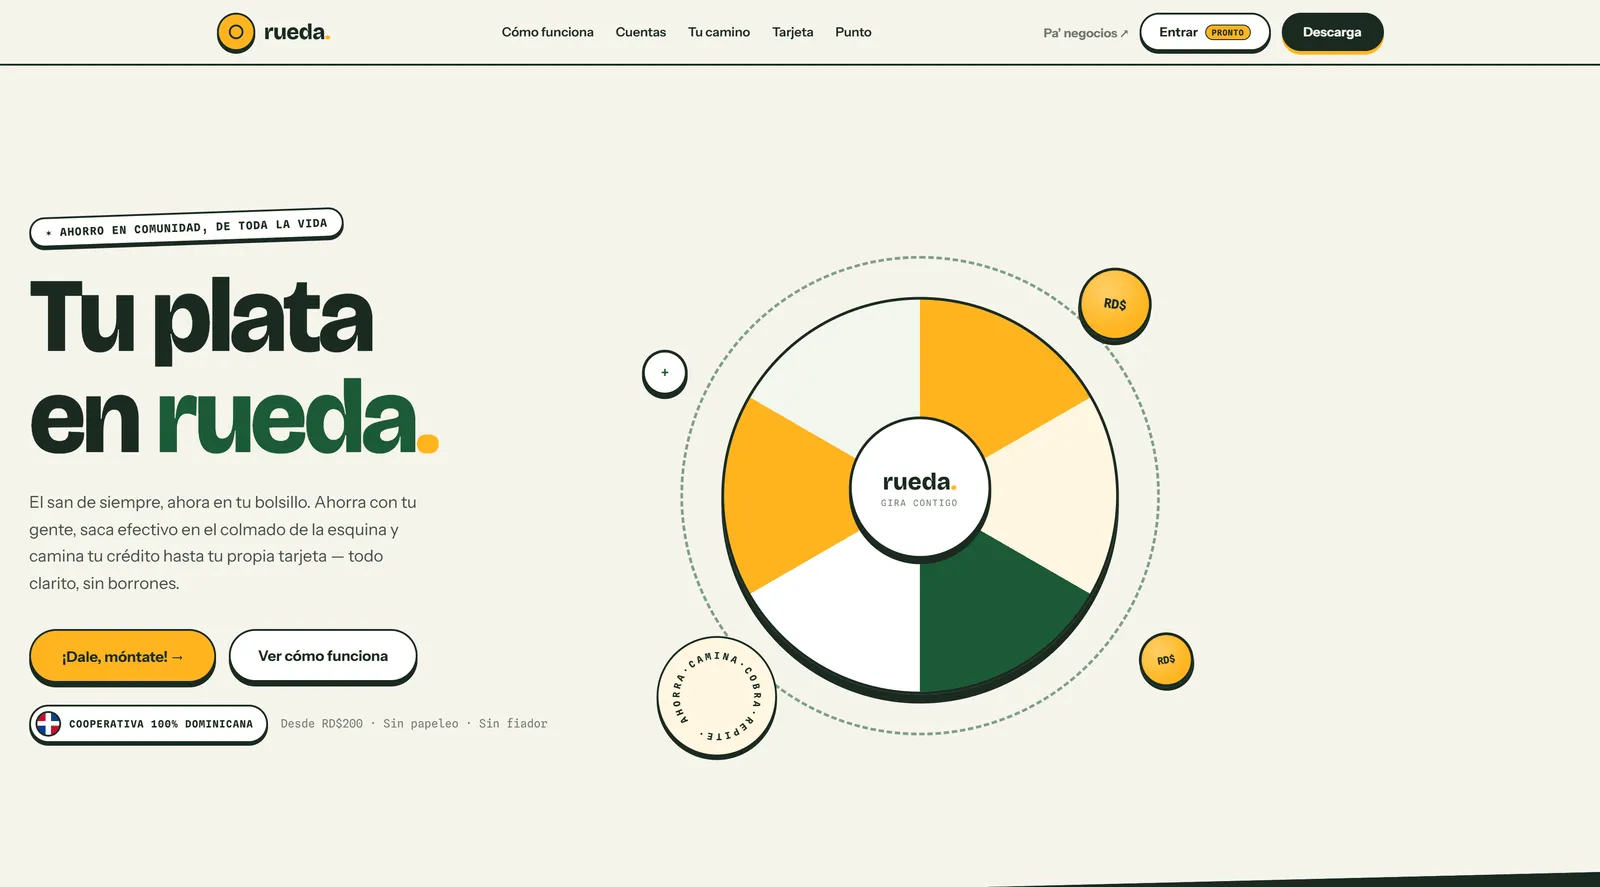
CoopRueda is a fully digital savings and credit cooperative for the Dominican Republic. The thesis is simple: people with no banking history already save in groups — the *san* — and already move cash at the corner store. Rueda is not there to teach them to save; it is there to give a guarantee, a record and a path to cheap credit for what they already do.
Membership does not go through the credit bureau: history is built from the inside, contribution by contribution, and reported outward to Data-Crédito and TransUnion. The result is credit between 1.2% and 2.0% monthly, against the 20% charged by the neighbourhood lender.
The product spans the member app, Point Mode for neighbourhood businesses, a website, a web portal, a back office, an internal console and an investor deck with the economic model and 2027–2031 projections.
// THE CHALLENGE
The financially excluded do not need education, they need infrastructure: they already save in a *san*, but the *san* collapses if someone defaults; they already move cash, but with no bank nearby; and when they need to borrow they pay 20% monthly because they have no history to show. All three had to be backed without asking for a credit file up front, and without falling under the banking-agent regime.
// THE SOLUTION
I designed the whole cooperative as a product, structured around four cycles — save, build history, use credit and move cash:
- 01Bureau-free membership: history is built from the inside and reported to Data-Crédito and TransUnion. A 9-step KYC with activation conditional on an initial RD$300 deposit.
- 02A savings circle with a guarantee fund: the circle does not collapse if someone defaults, which is exactly what breaks the informal *san*.
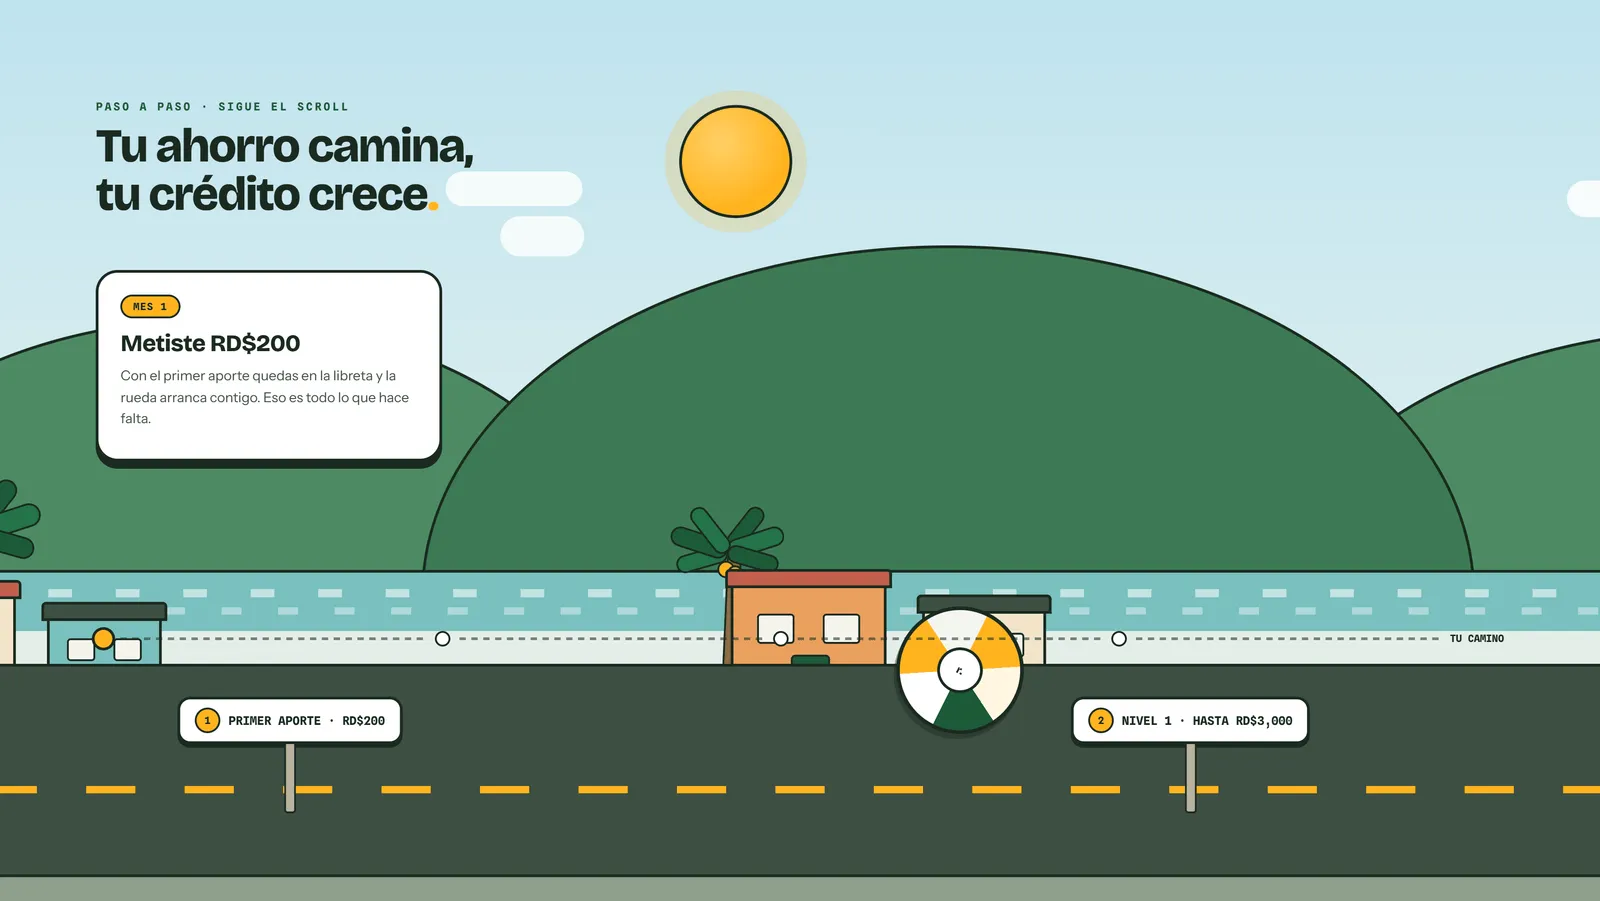
- 03A five-level path — Seed, Root, Steady, Hill and Harvest — where time rises rather than the amount: the limit goes from RD$15K to RD$100K and the rate drops from 1.8% to 1.2% monthly.
- 04A credit ladder: 0% Credit Builder, a funded card, a loan and a *san* advance.
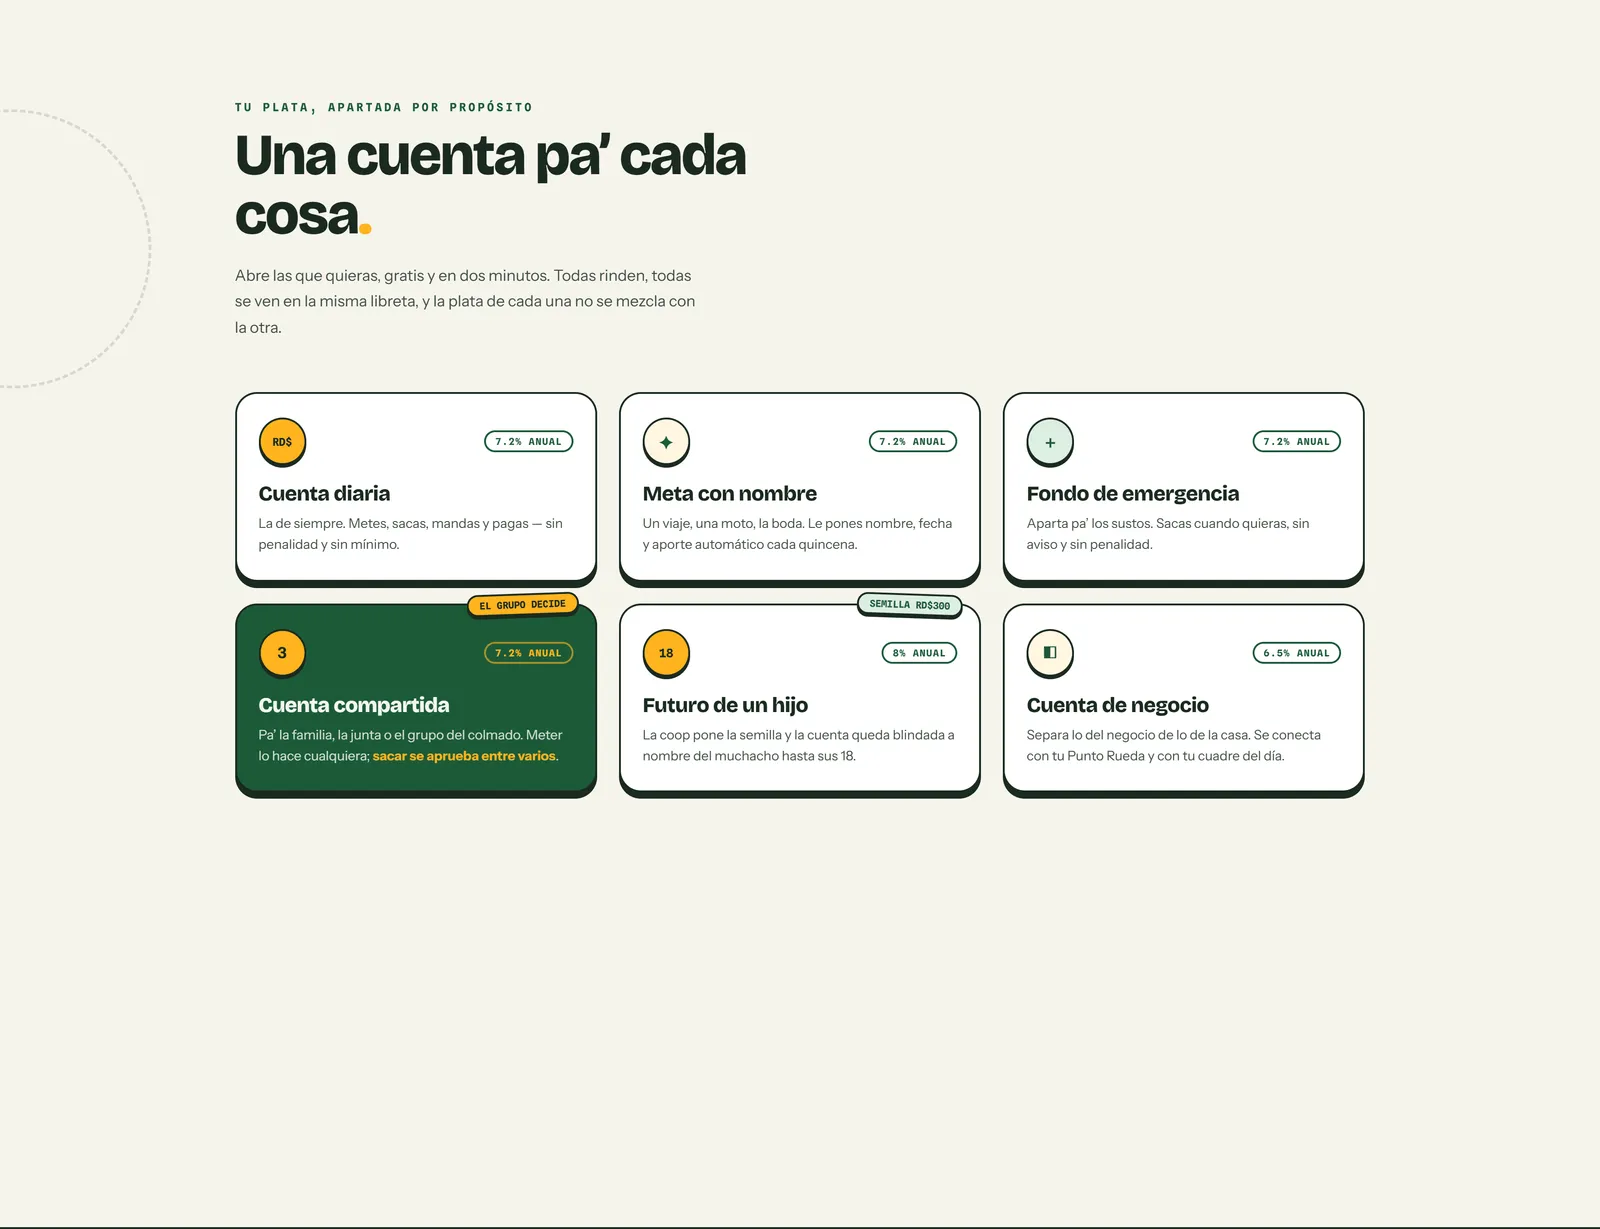
- 05Sixteen products with the price on the same line: 7 savings, 4 credit, the guaranteed *san* and 4 money-movement products, over three layers — a 7.5% Share contribution that counts as capital, a 5.5% locked Term Savings and a 3% Available Savings.
- 06Punto Rueda: the neighbourhood shop as a teller, with a single engine of one-time codes plus account-to-account P2P, float treated as two inventories — digital balance and till — with alerts for its four states, an end-of-day reconciliation and a regulatory framing that keeps it outside the banking-agent regime.
- 07A member app whose home changes with state — new, saving or in a *san* —, a balance card with no buttons, a central +MOVE button gathering every money action, and a returns projector over 1, 3, 5 and 10 years.
// SCREENS
// RESULTS
- A cooperative designed end to end: member app, Point Mode, website, portal, back office and internal console.
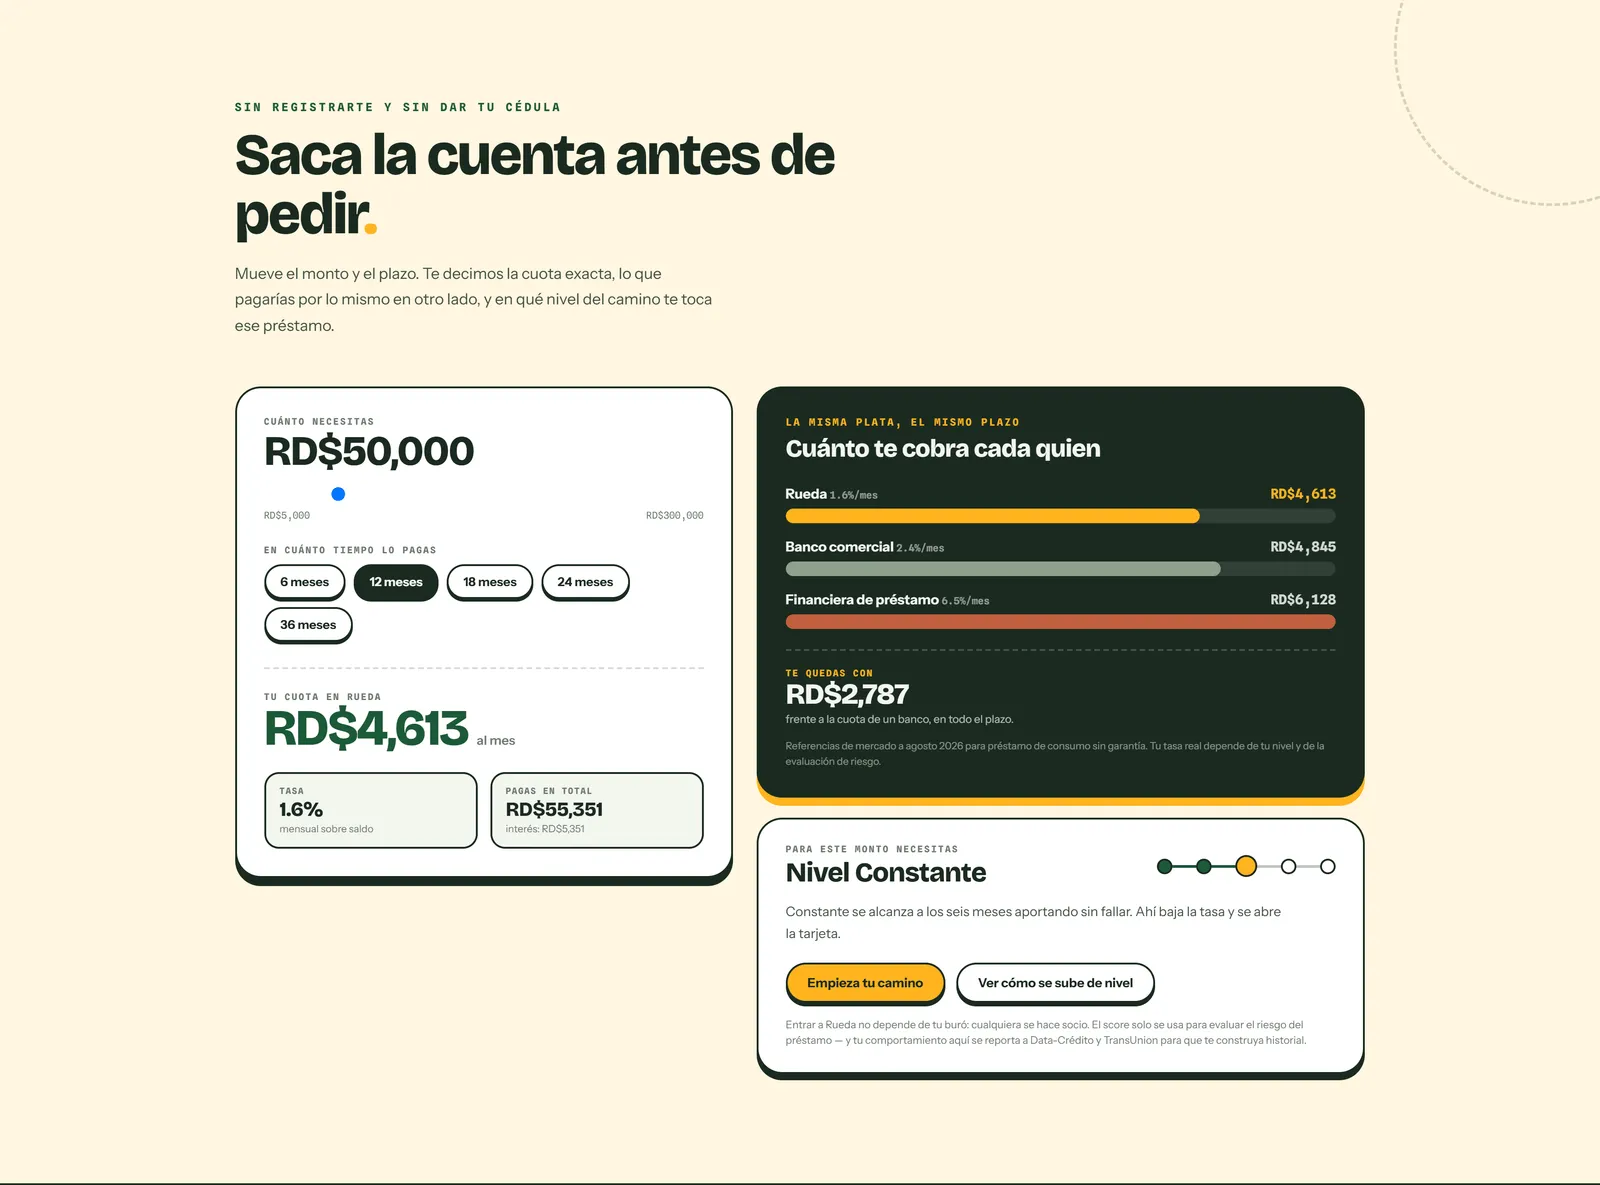
- Credit at 1.2%–2.0% monthly against the informal lender’s 20%, with the comparison visible in the simulator before you even apply.
- A history path that does not depend on the credit bureau to get in, yet reports to the bureaus on the way out.
- Economic model, fee schedule and 2027–2031 projections documented in an investor deck.